Pharmaceutical companies planning peptide or complex small-molecule launches are running into a familiar wall. A molecule clears development, but manufacturing slots at qualified facilities are booked out further than most teams expect.
Peptide demand climbed sharply over the past few years, driven largely by GLP-1 therapies. Manufacturing capacity hasn’t caught up yet. Companies used to securing commercial-scale capacity within months now plan around waits that stretch well beyond a year.
Knowing where API and peptide CDMO capacity actually stands today changes how companies plan. It shapes how companies time regulatory filings and negotiate supply agreements. It also determines which partners can deliver at the scale a molecule will eventually need.
What Does the Current State of API and Peptide CDMO Capacity Look Like?
The API and peptide CDMO sector is expanding, but not evenly. Capacity for complex small molecules has grown steadily, supported by established reactor infrastructure worldwide. Peptide manufacturing tells a different story.
Demand for peptide APIs has climbed faster than most manufacturers anticipated. The global peptide and oligonucleotide CDMO market was valued at $3.1 billion in 2025. That figure is projected to reach $8.1 billion by 2033. GLP-1 therapies drove much of that shift, resetting capacity expectations across the market. Contract manufacturers that once served a smaller peptide segment now see demand spanning metabolic disease and rare disease work.
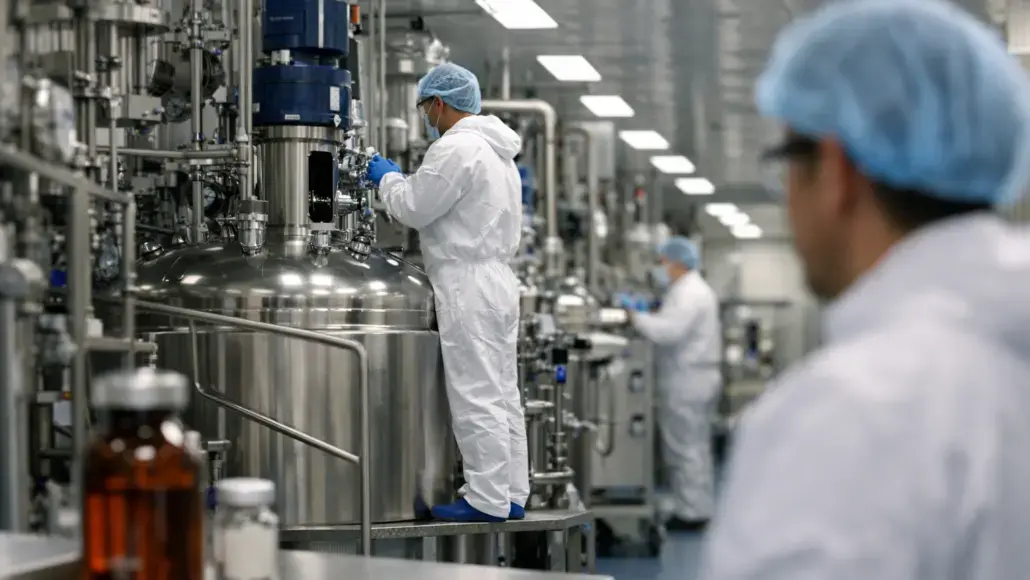
This surge has triggered a build-out cycle across the industry. New solid-phase and liquid-phase synthesis lines are coming online across North America and Europe. Facilities that once ran at a moderate scale are adding reactors and lyophilization capacity to meet demand.
The result is a market in transition. Commercial-scale peptide capacity is expanding to meet approved therapies. Capacity for earlier-stage, smaller-volume peptide work has grown more slowly. This gap shows up for companies moving a molecule from clinical to commercial scale. Securing a manufacturing slot now takes longer than it did two years ago. Planning around that reality has become part of how pharmaceutical companies approach outsourcing decisions.
Why Are Pharmaceutical Companies Turning to an API CDMO for Peptide Programs?
Pharmaceutical companies are turning to an API CDMO because building peptide manufacturing in-house is expensive and slow. Specialized reactors, purification systems, and regulatory infrastructure take years to set up before a single batch ships.
An API CDMO removes that burden by sharing its infrastructure across many clients. One facility can support several companies at once, which makes advanced capabilities accessible without the upfront cost. This is why the model works well for both ends of the market.
- Smaller biotech firms gain access to equipment and expertise they could never fund on their own
- Larger pharmaceutical companies add flexible capacity without expanding their own footprint
Peptide chemistry makes this choice even more practical. Techniques like solid-phase peptide synthesis and hybrid synthesis require deep, specialized know-how. Building that expertise internally can take years. Working with an established manufacturer skips most of that learning curve.
Regulatory track record adds further weight to the decision. A manufacturer that has already passed inspections by the FDA, EMA, and PMDA for peptide APIs brings proven reliability to every new project. That history lowers the risk for the pharmaceutical company as well.
Ultimately, outsourcing peptide manufacturing has become a long-term strategy, not just a cost-saving move. Companies want a partner who can support them from early development through to commercial supply, without a disruptive switch later on.
What Is Driving Capital Into Peptide CDMO Capacity Right Now?
Few areas of pharmaceutical manufacturing are drawing capital as quickly as peptides right now. The API and peptide CDMO sector is expanding to meet demand that keeps climbing.
The scale of that demand explains why. According to Grand View Research, the global peptide therapeutics market was worth about $140.9 billion in 2025. It is expected to reach $294.6 billion by 2033, growing at 8.7% a year.
This growth trajectory is pulling contract manufacturers into an active investment cycle. One recent peptide API facility expansion alone represents an investment of more than $500 million. That single project will add 25,000 liters of solid phase synthesis capacity by 2028.
Similar expansions are underway across Europe and Asia as manufacturers add reactor space and purification lines. Peptide manufacturing has moved from a smaller offering to a central part of many companies’ plans.
For pharmaceutical companies weighing an API and peptide CDMO partner today, this level of investment is a useful signal. Manufacturers expanding their peptide infrastructure are now positioning themselves for long-term relevance.
Where Do Bottlenecks Still Exist in API and Peptide CDMO Networks?
Bottlenecks in API and peptide CDMO networks persist even as capital investment accelerates. Building a plant takes years. A new facility announced today may not be ready to take on work for a long while.
Three constraints show up most often:
- Skilled talent: Process chemists and analytical scientists are in short supply. Quality staff face the same shortage. Facilities can be built faster than the teams needed to run them.
- Purification capacity: Complex peptides often need extensive purification. This step alone can take up more than half of the total production time and cost. Many facilities have strong synthesis capabilities but lack matching purification throughput. That mismatch slows the whole process down.
- Analytical work: Every new peptide needs its own testing methods built and validated before manufacturing starts. Skipping steps here risks quality problems later.
Together, these constraints explain why headline capacity numbers can be misleading. A facility with large reactors may still have long wait times. Companies should ask about actual lead times when they evaluate a manufacturing partner. Total capacity figures alone don’t tell the full story. A two-year queue makes little sense for a molecule nearing commercial launch.
How Is Geography Reshaping API and Peptide CDMO Supply Chains?
Geography is reshaping API and peptide CDMO supply chains as companies move away from relying on a single region. A string of supply disruptions in recent years has made this a real business priority.
India plays a central role in that shift. According to the India Brand Equity Foundation, India is the world’s third-largest producer of active pharmaceutical ingredients by volume. The country holds an 8% share of the global API industry. That scale is now extending into peptides, with Indian manufacturers adding dedicated synthesis and purification capacity.
Europe and the United States remain strong centers for peptide production, too. Companies based in these regions often value proximity to regulators and shorter shipping routes. Many pharmaceutical companies now qualify manufacturing partners across more than one region, rather than depending on a single site.
Working across multiple regions does add real complexity. Teams need to align quality systems and coordinate timelines across different sites. Moving a manufacturing process between locations also takes careful technical planning.
That effort is worth it for companies protecting the supply of critical molecules. Geographic diversification is, therefore, becoming standard practice when selecting API and peptide CDMO partners today.
FAQs
1. What’s the difference between an API CDMO and a peptide CDMO?
Many manufacturers offer both, but the chemistry differs. An API CDMO typically handles small-molecule synthesis, while a peptide CDMO specializes in solid-phase and liquid-phase peptide production. Companies with molecules in both categories benefit from partners covering each capability under one roof.
2. How long does it typically take to secure manufacturing slots with an API and peptide CDMO?
Lead times vary by molecule and scale, but peptide slots often have longer wait times than small-molecule capacity right now. Companies should start capacity discussions early, ideally before a molecule reaches late-stage development.
3. What should companies check beyond available capacity when choosing a manufacturing partner?
A few factors matter as much as raw capacity:
- Facility certifications and recent regulatory inspection history
- Experience in manufacturing similar molecules at a commercial scale
- Analytical and quality systems that match the project’s complexity
- Communication and technology transfer track record with other clients
4. Does tight peptide manufacturing capacity affect how pharmaceutical companies plan their launches?
Yes, when capacity is limited, companies often need to lock in manufacturing slots well before regulatory approval. This shifts planning earlier in the development timeline and makes partner selection a more strategic, forward-looking decision.