The European supplement industry has transformed from a niche market serving fitness enthusiasts and health-conscious individuals into a mainstream economic powerhouse. Worth billions of euros and continuing its upward trajectory, this sector has become an integral component of Europe’s healthcare and wellness landscape. From vitamins and minerals to protein powders and herbal remedies, dietary supplements have woven themselves into the daily routines of millions across the continent. Understanding the scale and growth velocity of this industry provides crucial insights into changing consumer behaviours, healthcare trends, and the evolving relationship Europeans have with preventative health measures.
Current Market Valuation and Scale
The European dietary supplement market has reached impressive proportions, with current valuations placing it between €19 billion and €22 billion annually, depending on which countries and product categories are included in the calculations. This positions Europe as the second-largest regional market globally, trailing only North America but surpassing the rapidly expanding Asian markets.
Germany leads the continent as the largest single market for supplements, accounting for approximately €2.5 billion in annual sales. The United Kingdom follows closely, with a market valued at around €1.8 billion, whilst France, Italy, and Spain complete the top five European markets. These five nations collectively represent roughly 65% of the entire European supplement industry’s value.
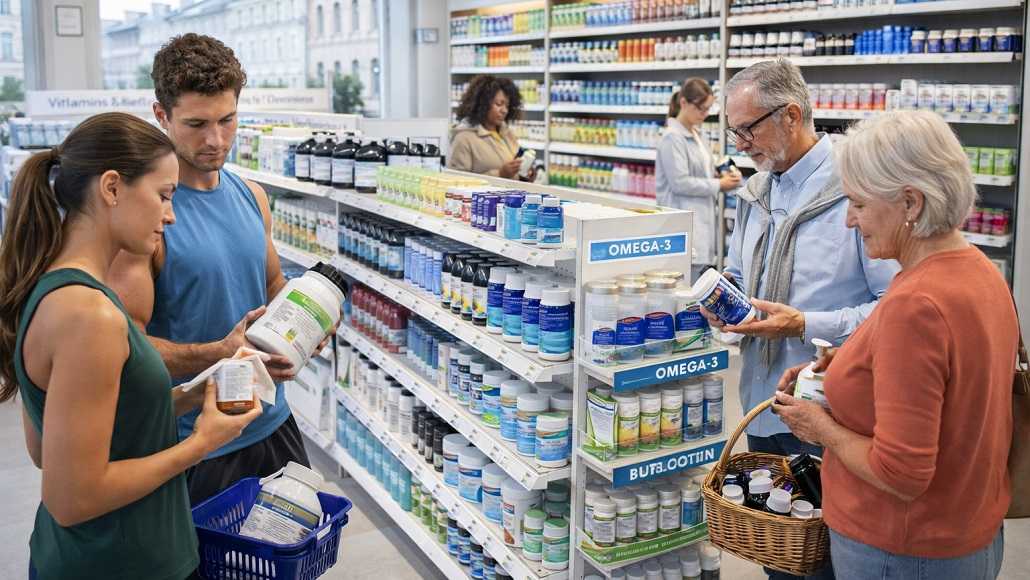
The scope of the market extends far beyond traditional multivitamins. Sports nutrition products, including protein powders and performance-enhancing supplements, constitute a significant segment worth approximately €4 billion across Europe. Weight management supplements account for another €3 billion, whilst vitamins and minerals – the traditional cornerstone of the industry – represent roughly €5.5 billion. Herbal and botanical supplements, omega-3 fatty acids, probiotics, and speciality supplements make up the remainder of this diverse marketplace.
Historical Growth Trajectory
To appreciate the industry’s current scale, one must examine its remarkable growth over the past two decades. At the turn of the millennium, the European supplement market was valued at approximately €6 billion, meaning it has more than tripled in size over twenty years. This represents a compound annual growth rate (CAGR) of approximately 5-7%, significantly outpacing general economic growth across the continent during the same period.
The growth has not been linear, however. The period between 2000 and 2008 saw steady but modest expansion, with annual growth rates hovering around 3-4%. The financial crisis of 2008-2009 temporarily slowed momentum, yet the industry proved remarkably resilient, recovering quickly as consumers increasingly viewed supplements as cost-effective preventative health measures compared to more expensive medical treatments.
The most dramatic acceleration occurred between 2015 and 2020, when the market grew at rates exceeding 8% annually in many European countries. This surge coincided with increased digital connectivity, the rise of health influencers, greater scientific literacy amongst consumers, and a broader cultural shift towards wellness and self-care.
The Pandemic Effect: An Unprecedented Acceleration
The COVID-19 pandemic served as an extraordinary catalyst for the supplement industry, compressing years of expected growth into mere months. During 2020 and 2021, the European market experienced growth rates of 10-15% annually, with some product categories such as immune support supplements seeing increases exceeding 30%.
Vitamin D sales skyrocketed as scientific discussions about its potential role in immune function became mainstream. Vitamin C, zinc, and elderberry supplements flew off shelves both physical and digital. Probiotics experienced renewed interest as consumers learned about the connection between gut health and immune function. This pandemic-driven boom brought an estimated 15-20 million new European consumers into the supplement market, many of whom have maintained their purchasing habits in the post-pandemic period.
The crisis also accelerated the digital transformation of supplement sales. E-commerce, which represented approximately 15% of supplement sales in 2019, surged to nearly 30% by 2021 and continues to grow. This shift has democratised access to specialised products and enabled smaller, innovative brands to reach consumers without the traditional barriers of retail distribution.
Key Growth Drivers
Several interconnected factors explain the supplement industry’s impressive expansion across Europe. The continent’s ageing population represents a fundamental driver, with the proportion of Europeans over 65 expected to reach 30% by 2050. This demographic shift creates sustained demand for supplements targeting age-related concerns such as bone health, cognitive function, and cardiovascular support.
Simultaneously, younger generations have embraced supplements with remarkable enthusiasm, though for different reasons. Millennials and Generation Z consumers view supplements as tools for optimisation and performance enhancement rather than mere disease prevention. They drive demand for sports nutrition, beauty supplements, and products promising cognitive enhancement.
Increased health awareness and scientific literacy have empowered consumers to take proactive roles in their health management. The proliferation of wearable technology and health-tracking apps has created a data-informed consumer base that monitors nutritional gaps and seeks targeted supplementation.
Professional endorsements have also gained influence. The gradual shift amongst some healthcare professionals from scepticism towards qualified support for appropriate supplementation has lent credibility to the industry. Simultaneously, fitness influencers, wellness advocates, and celebrity endorsements have mainstreamed supplement consumption across social media platforms.
Regulatory Landscape and Market Maturation
Europe’s stringent regulatory framework, primarily governed by the European Food Safety Authority (EFSA) and national regulators, has shaped the industry’s development. Whilst sometimes criticised by manufacturers for being overly restrictive, this regulatory rigour has arguably contributed to consumer confidence and market stability.
The regulation of health claims, in particular, has forced manufacturers to invest in research and substantiation, elevating the overall quality of products available to European consumers. This stands in contrast to less regulated markets where unsubstantiated claims proliferate. The result is a more mature, credible industry that has earned greater acceptance from both consumers and healthcare professionals.
Future Projections and Emerging Trends
Market analysts project continued robust growth for the European supplement industry, with forecasts suggesting the market could reach €30-35 billion by 2030. This would represent another 50% increase from current levels, driven by several emerging trends.
Personalised nutrition, enabled by advances in genomics and artificial intelligence, promises to revolutionise supplement recommendations. Companies are developing bespoke supplement formulations based on individual DNA analysis, microbiome composition, and lifestyle factors.
Sustainability and clean labelling are becoming non-negotiable for European consumers, particularly younger demographics. Brands emphasising organic ingredients, sustainable sourcing, environmentally friendly packaging, and transparent supply chains are capturing market share from traditional players.
The integration of supplements with digital health platforms and telemedicine services represents another frontier. Consumers increasingly expect holistic health solutions that combine professional guidance, monitoring technology, and targeted supplementation in seamless ecosystems.
Conclusion
The European supplement industry’s growth from a modest €6 billion market to today’s €20+ billion sector represents one of the most remarkable expansions in the consumer health landscape. This near-quadrupling in size over two decades reflects fundamental shifts in how Europeans approach health, wellness, and personal optimisation. The industry’s resilience through economic turbulence and its acceleration during the pandemic demonstrate both its economic robustness and its deepening integration into daily life across the continent. As scientific understanding advances, personalisation technologies mature, and health consciousness continues to intensify, the industry appears positioned for sustained growth well into the coming decades. The supplement sector has evolved from a peripheral health niche into a central pillar of Europe’s wellness economy, a transformation that shows no signs of reversing.